This page explains non-QM loans in Idaho, who they are for, and how they differ from traditional mortgages. It’s designed for Idaho homebuyers, investors, and self-employed individuals seeking flexible mortgage solutions.
A Crafted Purchase Strategy, Documentation, and Down Payment Review
We listen carefully, shop multiple wholesale lenders, and tailor your mortgage loan strategy for Idaho borrowers with precision — so the right loan type, including Non-QM loans in Idaho, fits your goals, documentation, credit profile, borrower contribution, property type, and long-term plan instead of a one-size-fits-all template.
That strategy can help first-time buyers, move-up buyers, self-employed borrowers, investors, and other non-traditional borrowers compare available mortgage options.
Reliable financing options may fit qualified borrowers with stable income documentation, standard credit history, acceptable debt-to-income ratios, and properties that meet traditional loans and traditional mortgage guidelines. These options can include purchase loans and standard refinance options that may affect interest rates, mortgage rates, monthly payment, and private mortgage insurance. When standard qualified mortgage guidelines do not fit, a non-qualified mortgage may be a practical alternative for borrowers with complex income, investment-property goals, or non-traditional documentation.
However, not all borrowers fit these traditional guidelines. For those who need more flexible options, non-QM loans may be the answer.
Non-QM loans are alternative home financing options for borrowers who may not fit standard qualified mortgage guidelines. Flexibility in documentation and underwriting guidelines can distinguish non-QM loans from some traditional mortgages and is one reason borrowers may work with an independent mortgage broker in Idaho. Non-QM loans may allow flexible income verification methods, but they still require lender review, credit evaluation, property review, ability-to-repay analysis where applicable, and program approval.
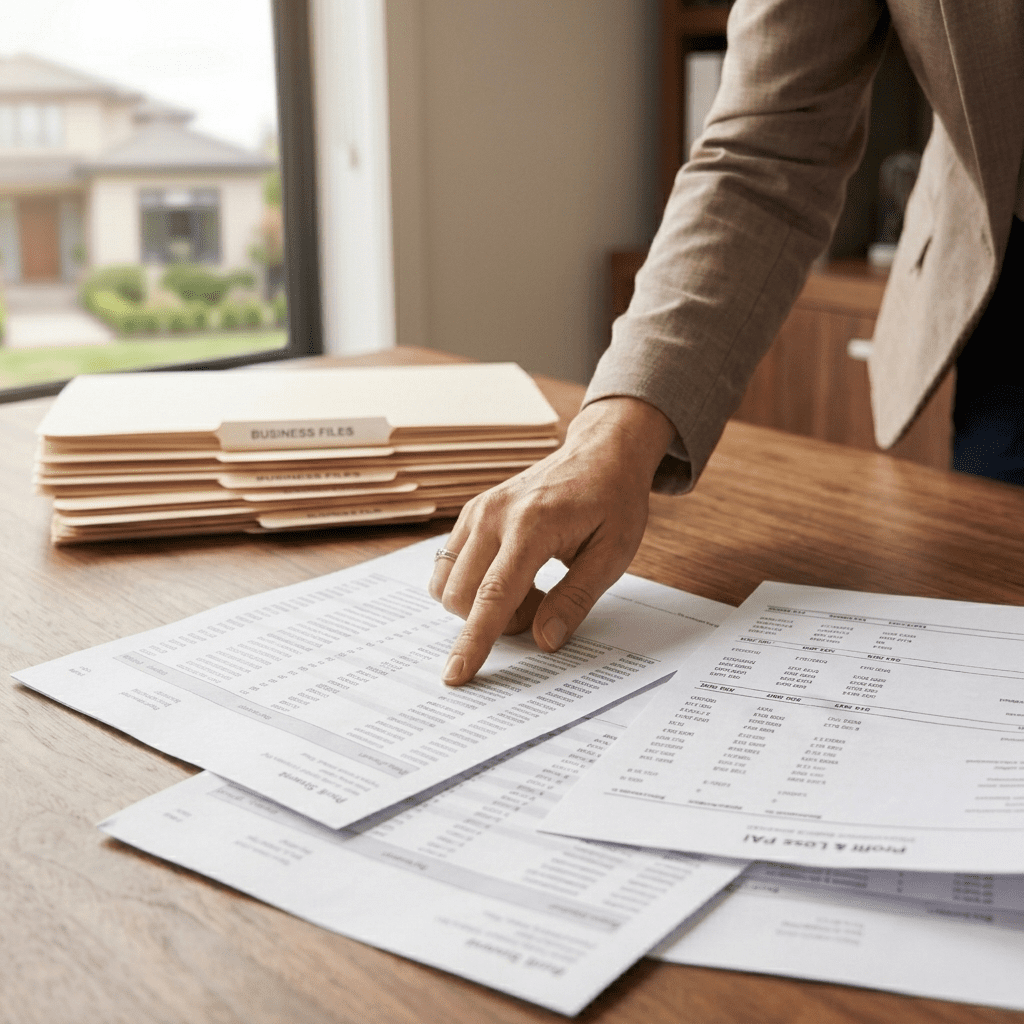
Where banks see risk, we see creative financial structure. Successful business owners and self-employed borrowers with non-traditional income are often asset-rich but structurally complex, and tax returns do not always reflect their full qualifying picture.
For some borrowers, alternative documentation such as bank deposits, business bank statements, P&L statements, 1099 income, rental-property cash flow, or significant assets may support lender review. Recent credit events may be evaluated differently by some Non-QM lenders, but approval still depends on program guidelines, borrower strength, property type, equity, documentation, and underwriting.
Successful business owners and 1099 professionals are often asset-rich but structurally complex. At Home Lending can help compare Bank Statement, P&L, 1099, asset-based lending, and DSCR programs, including bank statement programs and a bank statement only loan, when those options are available through participating lenders. These programs may help qualified self-employed borrowers use bank statements or business bank statements as part of income review instead of relying only on traditional income documentation. A DSCR loan can help some real estate investors qualify using rental income, the property’s cash flow, and debt service coverage ratio rather than personal income, depending on lender and property requirements.
The 12-day superpower
At Home Lending focuses on efficient communication, document collection, wholesale lender coordination, and support from a dedicated loan officer. Complex scenarios such as purchase, refinance, cash-out, Non-QM loans, DSCR loans, bank statement loans, and renovation-cost planning can move more smoothly when borrower documentation, appraisal, title, underwriting, and closing conditions are organized early. You can also compare options through no-obligation mortgage quotes.
Idaho mortgage brokers, mortgage lenders, and mortgage loan originators are regulated through the Idaho Department of Finance and NMLS for applicable mortgage activities.